
Stembrook Market Review - Third Quarter 2026
Market UpdatesThe second-quarter rally stalled in the third quarter. Oil prices climbed again, inflation picked back up, and the Federal Reserve raised rates for the first time since 2023. US large-cap stocks still rose 2.3%,1 but small caps fell nearly 8%2 and bonds had their worst quarter in 4 years. This was the weakest quarter for bonds since the interest rate hike of 2022. Several factors contributed to the divergence in market returns, which we highlight below.
Last quarter, we expressed concern that the unresolved conflict in the Middle East around the Strait of Hormuz could put upward pressure on oil prices. Brent crude ended June near $70 and by the end of the quarter, it was trading above $102 per barrel, after briefly topping $130 in mid-September.3 As a result, energy stocks gained 17% in the quarter and are up over 40% year-to-date, as energy producers have improved their margins thanks to higher oil prices.4
Annual CPI inflation rose to 3.7% in September from 3.4% in August, led by the surge in energy prices.5 Citing concerns about inflation, the Fed raised its policy rate by 0.25% to a range of 3.75%–4.00%. The 10-year Treasury yield ended the quarter near 5.3%.6 This rise in yields caused downward pressure on prices for existing bondholders. The rise in rates over the past year is highlighted in the chart below, titled "Rising Yields."
Rising Yields
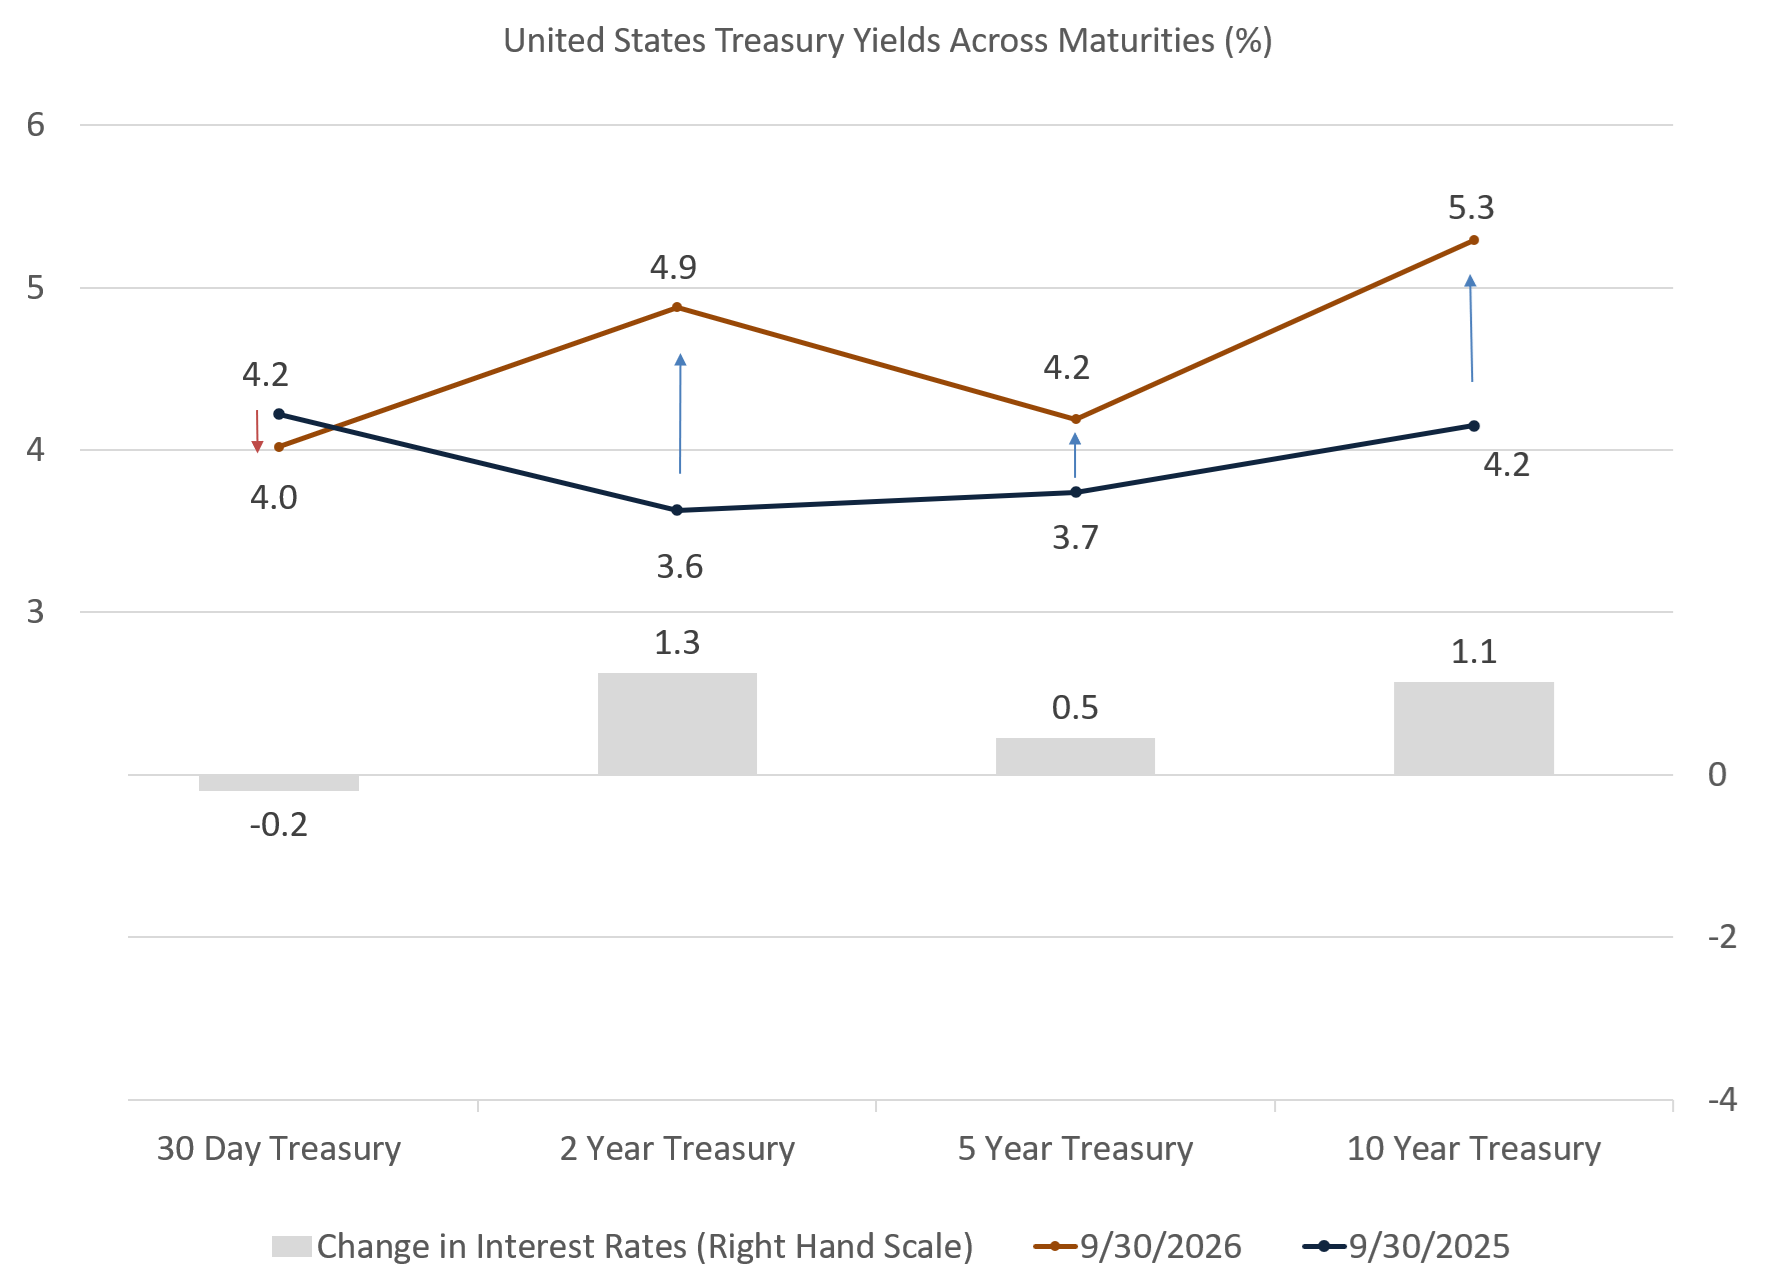 Interest rates have increased by 0.5 to 1.3 percentage points across the Treasury curve with the exception of short-term rates, which have remained nearly unchanged over the past year.
Our proprietary models forecast long-term, pre-tax returns ranging from 4% to 5% for fixed income-like asset classes and 9% to 10% for equity-like asset classes (see Expected Market Returns and Risks table). More detailed observations and current portfolio positioning are outlined in the following comments.
Expected Market Returns and Risks 7-10 Year Horizon
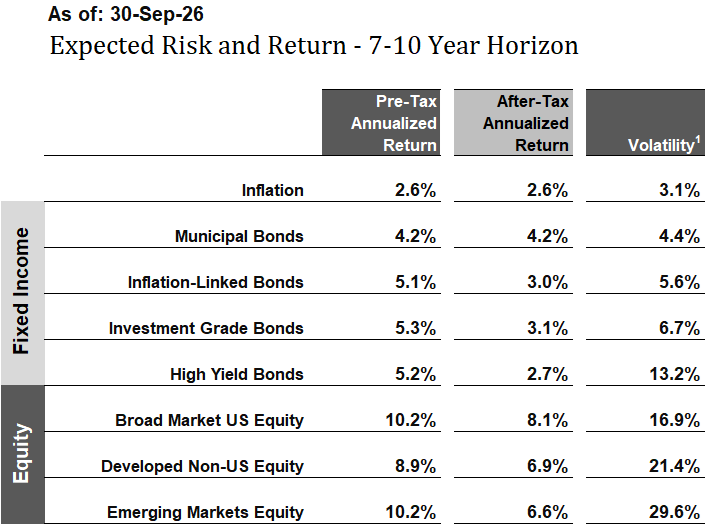
A sampling of return expectations produced by our models. Expected returns are projections and are not guaranteed.
Historical Market Returns
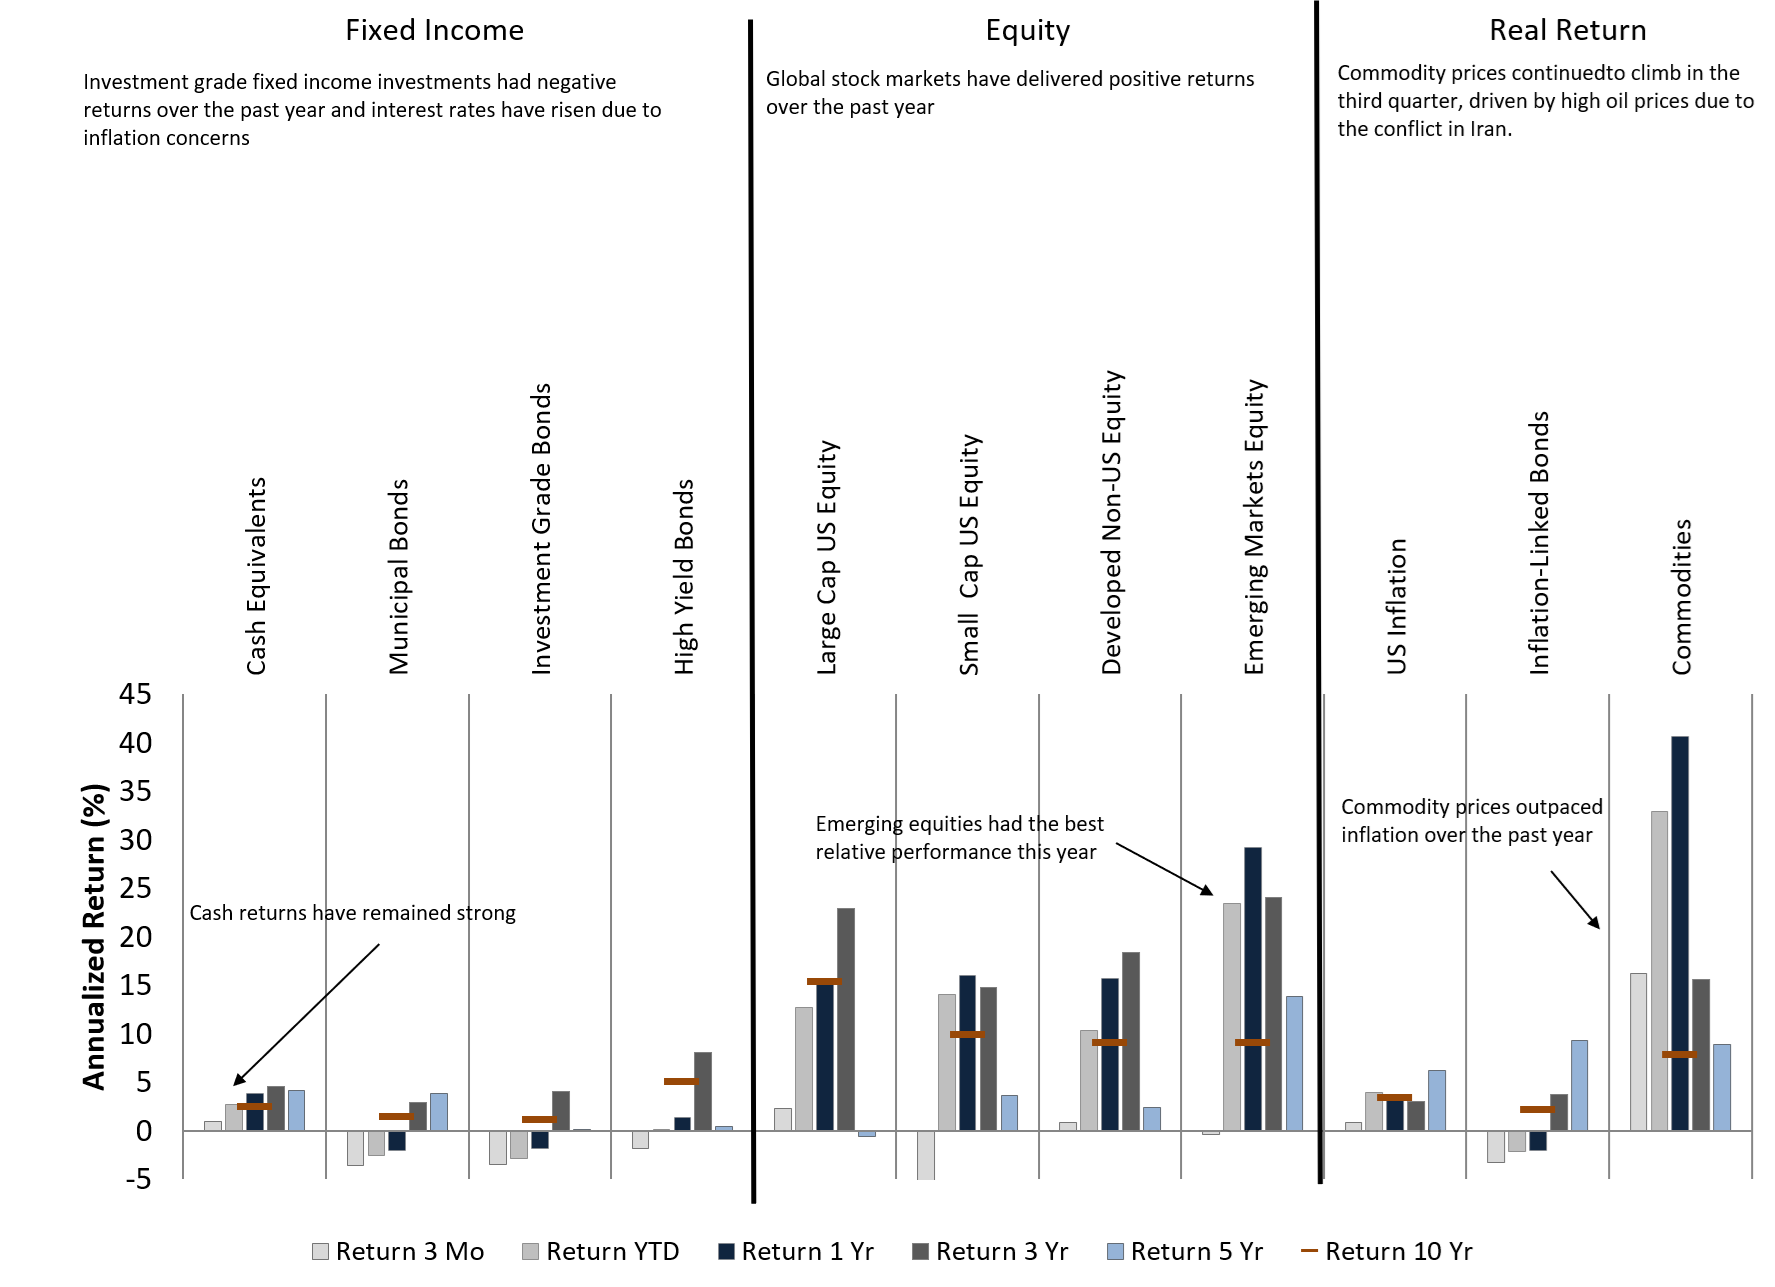 Historical market returns as of September 30th, 2026. Note that looking backwards at recent returns is not a reliable method of predicting future returns.
Yields Across Asset Classes
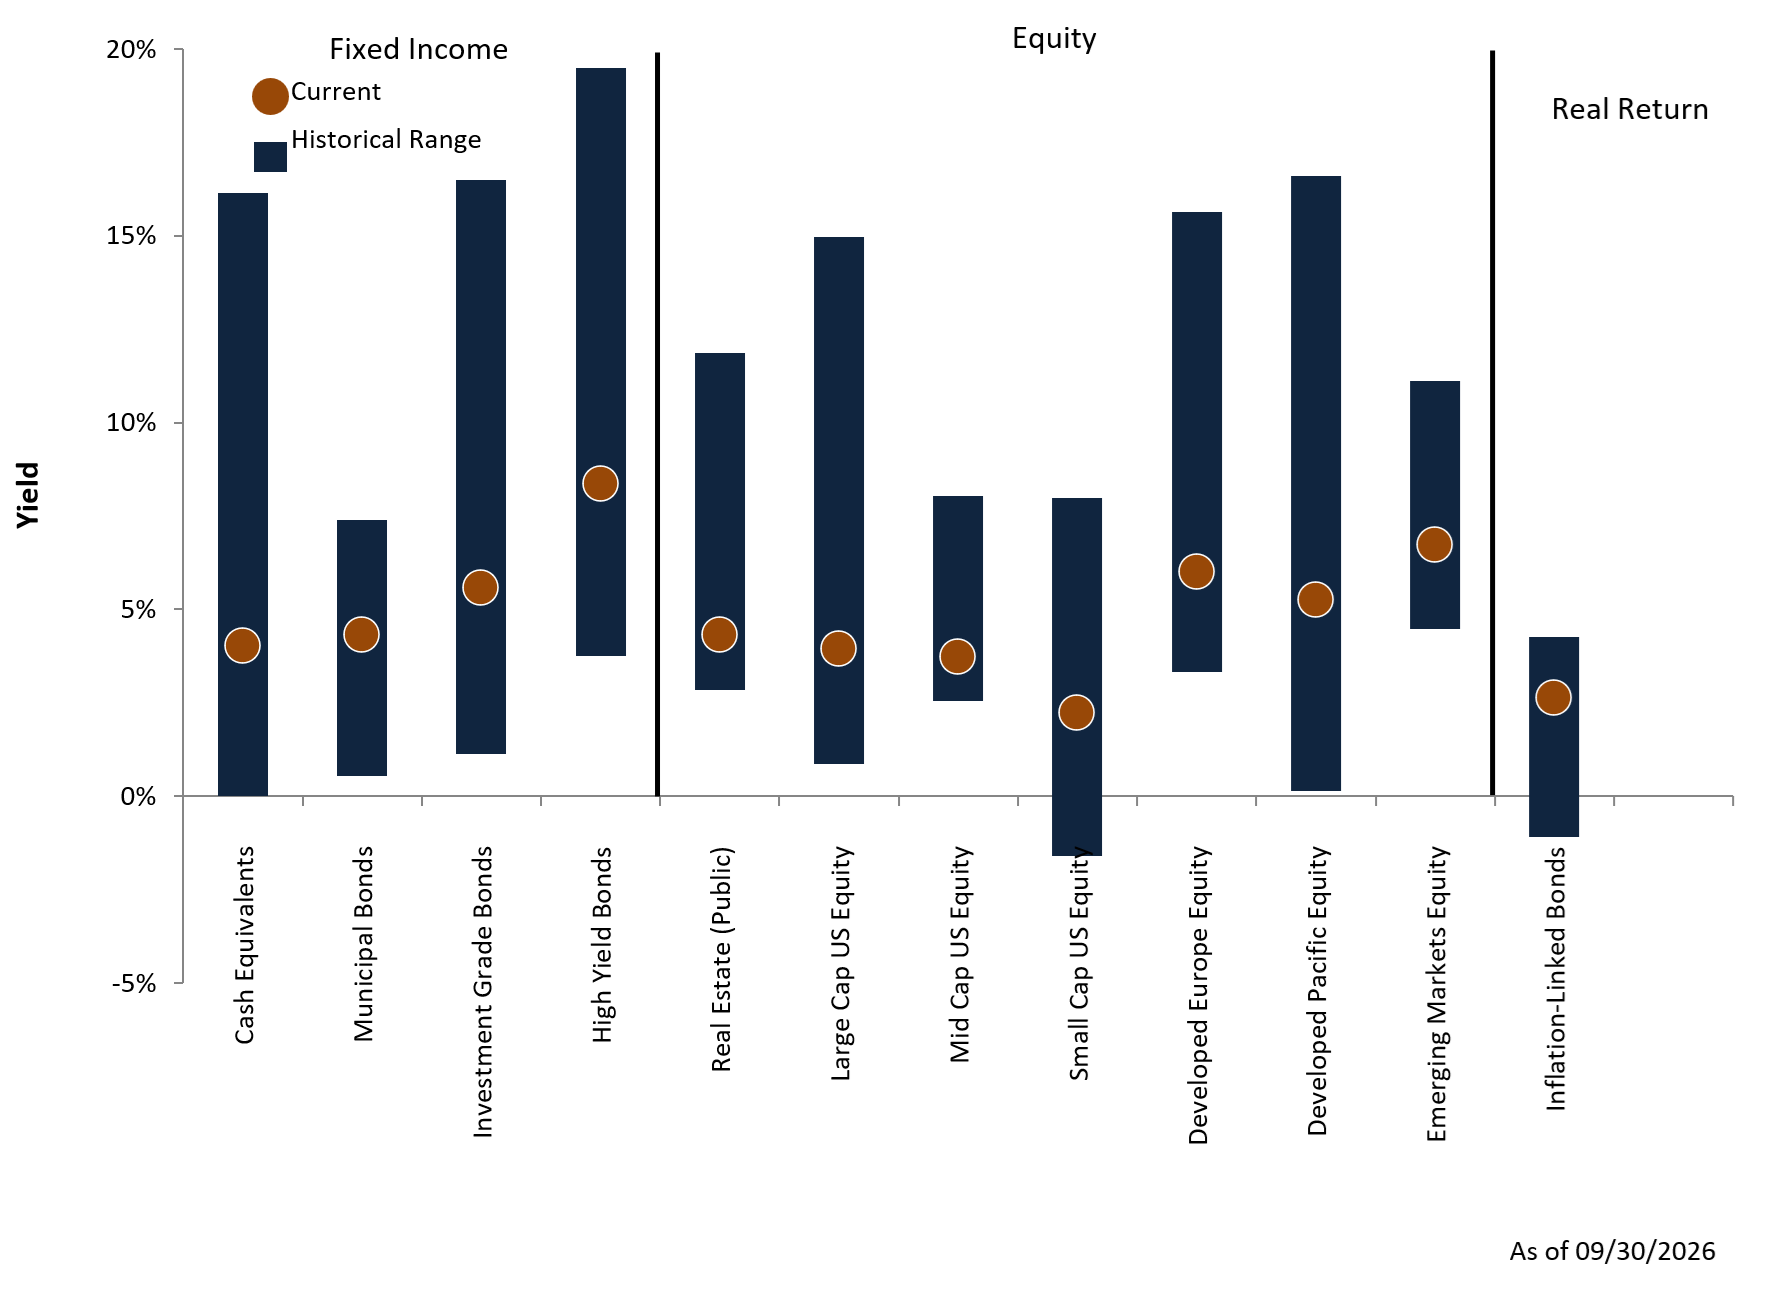 Yields are an indicator of future returns. Orange dots show current yields, blue bars show historical ranges.
Economic Backdrop
- US real GDP grew at a 3.4% annualized rate, up from 2.2% in the second quarter, led by business investment and consumer spending.7
- In its October World Economic Outlook, the IMF raised its 2026 global growth forecast slightly, to 3.1% from 3.0% in July. The outlook remains at 3.4% for 2027. It expects global inflation to stay well above its long-term average.8
- Emerging economies are expected to see a deceleration in growth. Growth in emerging economies is expected to slow to 3.7% in 2026, followed by an increase to 4.4% next year, with continued strength in Asian markets.8
- The FOMC voted unanimously in September to raise the federal funds target by 0.25%, to 3.75%–4.00%. At quarter-end, markets were pricing about 0.75% of additional hikes by June 2027.
- Global stocks posted a modest 1.1% gain, driven by US large-cap performance.9
- Within the US market, value stocks led the way, rising 5.6%, compared to growth stocks, which rose just over 1% .10
- Non-US developed markets stocks were up a modest 1% in the quarter.11
- Despite a weaker third quarter return of -0.4%, Emerging Markets equities continue to be the top regional performers. The index remains up over 23% for the year-to-date.12 Returns in this region have been primarily driven by a select group of stocks in South Korea.
- Concerns about inflation and a rise in interest rates put a damper on bond returns in the third quarter, investment grade bonds in the US fell by 3.5%.13
- Longer-duration municipal bonds, which are more sensitive to changes in interest rates, were down by over 6% in the quarter.14
- One of the few bright spots in fixed income was leveraged loans, which benefited from their floating-rate structure, which requires issuers to raise coupon payments when interest rates go up. The asset class was up nearly 2% in the quarter.15
Global Asset Class Returns
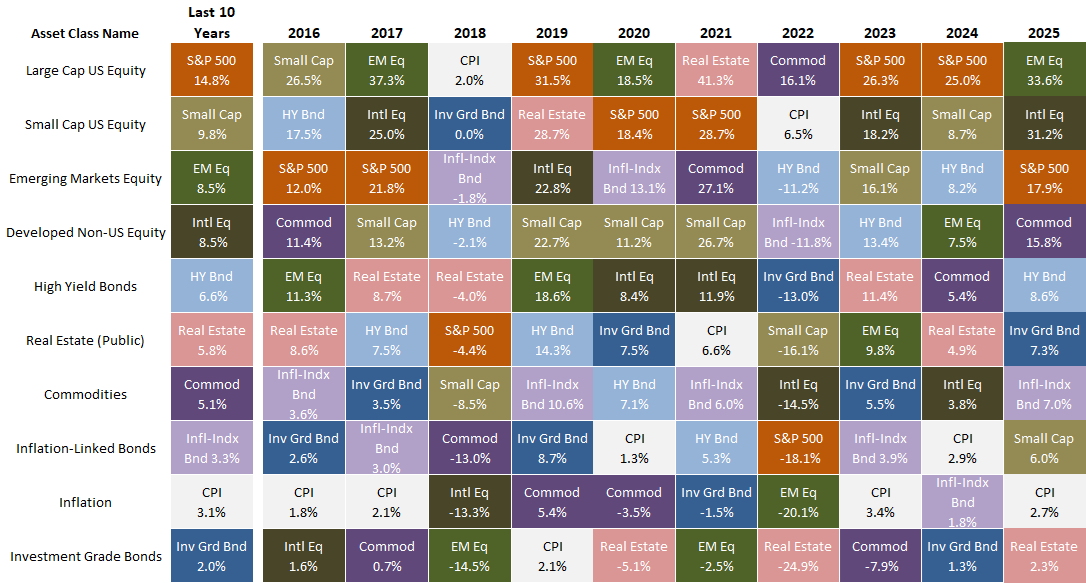
Returns are arranged in columns, by year. Each color represents a different asset class. Each year, the leaders and laggards tend to shift. Diversification across a range of asset classes can smooth returns and enhance growth.
- We maintain our neutral duration position in fixed income portfolios as interest rates have risen to levels closer to historical averages.
- We maintain our neutral allocation to emerging market equities.
- We maintain a neutral exposure to large-cap US equities within a global portfolio.
- After a strong first half of 2026, we have sold our position in small and mid-cap equities in the United States.
- We favor lower-priced, value-oriented equities, both in the US and abroad, which have historically tended to outperform the broad market over time with less volatility. We are optimistic about their return potential going forward.
We continue to focus our efforts on helping you meet your financial objectives by following our disciplined investment approach. Our approach uses return and risk models, incorporating fundamental valuations and tax-efficient strategies. This investment discipline is tailored to your individual situation in our continuing effort to craft and implement your customized investment solution.
As we approach the end of the year, please keep tax planning and gifting strategies in mind. If you would like to discuss your specific tax situation or plans for year-end gifting, please let us know and we can schedule a time to speak.
As always, we thank you for placing your trust in our investment management and advice and welcome your questions and comments at any time.
Peter & Tom
Endnotes and Sources:
Text:
- Morningstar: S&P 500 TR USD: 6/30/2026 - 9/30/2026.
- Morningstar: S&P SmallCap 600 TR USD: 6/30/2026 - 9/30/2026.
- EIA: Crude Spot Price. 6/30/2026 - 9/30/2026.
- Morningstar S&P 500 Energy. 6/30/2026 - 9/30/2026. 12/31/2025 - 9/30/2026.
- Bureau of Labor Statistics: CPI. 6/30/2026 - 9/30/2026.
- Federal Reserve: 10-year Treasury as of 9/30/2026.
- BEA - United States Real GDP Growth. Third Quarter Estimate, Second Quarter 2026.
- IMF World Economic Outlook Update: October 2026.
- Morningstar: MSCI ACWI NR USD. 6/30/2026 - 9/30/2026.
- Morningstar: S&P 500 Value and S&P 500 Growth. 6/30/2026 - 9/30/2026.
- Morningstar: MSCI EAFE. 6/30/2026 - 9/30/2026.
- Morningstar: MSCI Emerging Markets NR USD. 6/30/2026 - 9/30/2026. 12/31/2025 - 9/30/2026.
- Morningstar: Bloomberg US Aggregate Bond Index. 6/30/2026 - 9/30/2026.
- Morningstar: Bloomberg Municipal Bond Index. 6/30/2026 - 9/30/2026.
- Morningstar: Morningstar LSTA US Leveraged Loan Index. 6/30/2026 - 9/30/2026.
Charts:
Rising Yields
Source: The Federal Reserve, Stembrook Research. As of 9/30/2026.
Expected Market Returns and Risks, 7-10 Year Horizon: As of 9/30/2026.
Source: Stembrook Research.
(1) Volatility is measured in terms of Standard Deviation. Standard deviation is the statistical measurement of dispersion about an average, which depicts how widely a stock or portfolio’s returns varied over a certain period of time. Investors use the standard deviation of historical performance to try to predict the range of returns that is most likely for a given investment. When an investment has a high standard deviation, the predicted range of performance is wide, implying greater volatility. If an investment’s returns follow a normal distribution, then approximately 68 percent of the time they will fall within one standard deviation of the mean return of the investment, and 95 percent of the time within two standard deviations. For example, for a portfolio with a mean annual return of 10 percent and a standard deviation of two percent, you would expect the return to be between 8 and 12 percent about 68 percent of the time, and between 6 and 14 percent about 95 percent of the time. Source: Morningstar.
Historical Market Returns: As of 9/30/2026.
Source: Morningstar, Stembrook Research.
Indices: Bloomberg Barclays U.S Treasury Bills 1-3 Month Total Return, Bloomberg Barclays Municipal Bond 5 Year (4-6) Total Return, Bloomberg Barclays US Aggregate Bond Total Return, Bloomberg Barclays US Corporate High Yield Total Return, FTSE All Equity REIT Total Return, S&P 500 Composite Total Return, S&P SmallCap 600 Total Return, MSCI EAFE Total Return, MSCI EM (Emerging Markets) Total Return, Consumer Price Index – US, S&P 10 Year US TIPS Total Return, Bloomberg Commodity (Total Return) Index.
Yields Across Asset Classes: As of 9/30/206.
Sources: Cash Equivalents Yields since March 1976. Ibbotson, Federal Reserve Bank, Thomson Reuters, Municipal Bond Yields since March 1988. Barclays Capital, Charles Schwab, BofA Merrill Lynch, Standard & Poor's/Investortools Municipal Bond Indices, Investment Grade Bond Yields since March 1976. Barclays Capital, High Yield since December 1984. BofA Merrill Lynch, Barclays Capital, Real Estate (Public) Earnings Yield since March 1976. NAREIT all Equity, Large Cap US Equity Earnings Yield since March 1976. Standard & Poor's, BARRA, Mid Cap US Equity Earnings Yield since June 1991. Standard & Poor's, BARRA, Small Cap US Equity Earnings Yield since December 1993. Standard & Poor’s, BARRA, Developed Europe Equity Earnings Yield since March 1976. MSCI Europe, Standard & Poor's Europe 350, Developed Pacific Equity Earnings Yield since March 1976. MSCI Pacific, S&P/Citi PMI Asia Pacific, S&P Asia 50, Emerging Market Equity Earnings Yield since December 1998, Inflation-Linked Bond Real Yield to Maturity since March 1997. Citi Yield Book, Federal Reserve Bank. Note: Yields are not perfect predictors of future returns and should not be used in isolation.
Global Asset Class Returns: As of 12/31/2025.
Source: Thomson Reuters, Bloomberg, Morningstar, Stembrook Research.
Indices: Consumer Price Index – US, US 30-Day Treasury Bills, Bloomberg Barclays US Treasury Bills: 1-3 Month Index, Citigroup Inflation-Linked Index, S&P 10 Year US TIPS Index, Bloomberg Barclays US Aggregate Bond Index, BofA Merrill Lynch US High Yield Cash Pay, Bloomberg Barclays US Corporate High Yield Index, Dow Jones Wilshire REIT Index, FTSE All Equity REIT Index, S&P 500 Composite Total Return, S&P SmallCap 600 Total Return, MSCI EAFE Index, MSCI EM (Emerging Markets) Index, Dow Jones AIG Commodity (Totl Ret) Index, Bloomberg Commodity Index.
Disclosures
This material is intended to inform you of products and services offered by Stembrook Asset Management, LLC (“Stembrook”). Stembrook is a US Securities and Exchange Commission Registered Investment Advisor.
This material is not intended as an offer or solicitation for the purchase or sale of any financial instrument.
We believe the information contained in this material to be reliable but do not warrant its accuracy or completeness. The opinions, estimates, and investment strategies and views expressed in this document constitute the judgment of Stembrook, based on current market conditions and are subject to change without notice. The investment strategies stated here may differ from those expressed for other purposes or in other context.
Past performance is not indicative of future results.
The obligations and securities sold, offered, or recommended are not deposits and are not insured by the FDIC, the Federal Reserve Bank, or any governmental agency.
The views and strategies described herein may not be suitable for all investors. This material is presented with the understanding that it is not rendering accounting, legal or tax advice. Please consult your legal or tax adviser concerning such matters.
Important note regarding Stembrook’s capital market expectations.
The capital market expectations developed by Stembrook Asset Management are estimates of both a central tendency of asset class behavior and a probable range of asset class behavior over a long-term horizon. These estimates are one of many inputs used in the portfolio construction process, and should not be used independently. These expectations should not be construed as the returns that will be achieved, but merely those that may be achieved if certain assumptions hold true. Also note that each client's portfolio may differ given specific goals and constraints applied to the portfolio construction process.
Additional information is available upon request.